Your business may be profitable, but mortgage lenders calculate qualifying income differently. Learn how Florida business owners can prepare for mortgage approval.
For context on whether now is a good time to buy, see Redfin’s analysis: Is Now a Good Time to Buy a House?
Your Business Is Profitable. Why Doesn’t Your Mortgage Lender See It?
Owning a successful business doesn’t automatically make qualifying for a mortgage easy. For many Florida business owners, one of the biggest surprises during the homebuying process is discovering that the income they earn, the revenue their business generates, and the income a mortgage lender can use for qualification may be three different numbers. That distinction becomes particularly important when mortgage rates rise and affordability becomes more challenging. Understanding how lenders evaluate self-employed income can help business owners prepare earlier, avoid surprises, and identify appropriate financing options.
Mortgage Rates Are Increasing the Importance of Qualifying Income
Mortgage rates have climbed significantly in recent weeks. As of the October 8 market update used for this article, the reported Freddie Mac national average 30-year fixed mortgage rate was 7.40%, up from 7.28% the previous week. Mortgage News Daily’s daily average was reported at approximately 7.50%. These figures represent different surveys and should not be confused with personalized rate quotes. Higher rates increase the monthly principal-and-interest payment on a given loan amount. For example, a hypothetical $320,000 mortgage over 30 years costs approximately $1,981 per month in principal and interest at 6.30%, versus approximately $2,216 at 7.40%—a difference of about $235 monthly. This illustration excludes taxes, insurance, mortgage insurance and other expenses. For a self-employed borrower, the higher payment may require more qualifying income.
Source: Freddie Mac, Mortgage News Daily
Business Revenue Is Not the Same as Qualifying Income
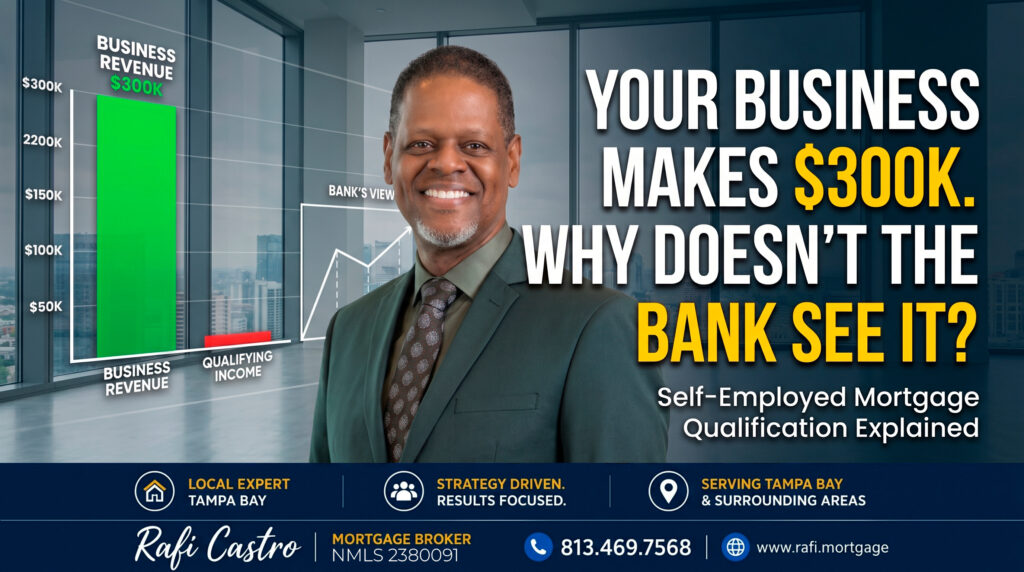
Suppose a Florida business owner operates a company generating $350,000 in annual revenue. The business has employees, operating expenses, equipment costs, and other legitimate deductions. After expenses, the company’s taxable income may be substantially lower than gross revenue. A mortgage lender generally cannot use the $350,000 revenue figure as the borrower’s personal qualifying income. Instead, the lender evaluates financial documents and applicable underwriting guidelines to determine what income is stable, recurring, and available to support the proposed mortgage. The calculation depends on the borrower’s business structure, ownership interest, income history, and financial obligations. This is why a borrower may feel financially comfortable while the initial mortgage-income calculation appears unexpectedly low.
How Mortgage Lenders Evaluate Self-Employed Borrowers
Traditional mortgage programs generally require a review of documented income. For conventional loans, Fannie Mae generally considers borrowers with ownership interests of 25% or more in a business to be self-employed. Its guidelines emphasize income stability, business viability, and the ability of the business to continue generating sufficient income. Depending on circumstances, lenders may review personal and business tax returns, applicable schedules, K-1s, and other financial records. A two-year income history is commonly used, although specific exceptions and alternative documentation requirements may apply. The lender may also examine trends in revenue, expenses, and earnings. A business showing declining income may require additional analysis. The objective is to determine sustainable qualifying income—not simply identify the largest number.
Source: Fannie Mae
Can Mortgage Lenders Add Back Tax Deductions?
Sometimes. Certain expenses reported on business tax returns may receive special treatment in mortgage cash-flow analysis. Depreciation is one example that may be considered under applicable guidelines. However, borrowers should not assume every deduction can be added back. Different expenses receive different treatment, and eligibility depends on the business structure, documentation, and mortgage program. A lender may also need to consider business losses, debt obligations, and other adjustments that reduce qualifying income. This is why reviewing complete tax returns is generally more useful than looking only at adjusted gross income or a profit-and-loss statement.
Should Business Owners Stop Taking Tax Deductions Before Buying?
Not automatically. Business owners should continue working with qualified tax professionals to make appropriate tax decisions. Reducing legitimate deductions solely to pursue mortgage approval may create unnecessary tax consequences and does not guarantee better financing. A more productive approach is to coordinate mortgage planning with tax planning. If a business owner expects to purchase a home within the next year, an early conversation with both professionals may help identify potential qualification issues. That review should happen before filing decisions are made, not after a purchase contract is signed.
What About Bank-Statement Mortgage Programs?
Traditional tax-return-based financing isn’t the only possible option. Some Florida borrowers may qualify for alternative-documentation mortgages that evaluate eligible bank deposits rather than relying exclusively on traditional tax-return income calculations. These are often called bank-statement mortgages. They can be useful for certain self-employed borrowers whose tax returns do not fully reflect the financial picture considered under the program. However, bank-statement programs are not automatically easier or less expensive. They may require different down payments, credit profiles, reserves, documentation, and interest-rate pricing. Eligible deposits may also be adjusted for business expenses. The appropriate program depends on the borrower’s circumstances. Traditional conventional, FHA, VA, or USDA financing may still be preferable when the borrower qualifies and meets program requirements.
Tampa Bay’s Housing Market Creates Opportunities and Challenges
Financing preparation is especially relevant in the Tampa Bay market. The September 2026 Tampa–St. Petersburg–Clearwater metropolitan market figures referenced in this week’s research showed a median listing price of approximately $385,398, down 6.6% year over year, with roughly 27.5% of active listings experiencing a price reduction. Homes spent a median 76 days on the market. These numbers suggest some sellers are adjusting expectations and buyers may find negotiating opportunities. However, active inventory was also reported down approximately 3.8% year over year. Conditions depend on neighborhood, property type, price range, and condition. For a business owner, identifying a negotiable property is only part of the process: the financing must work as well.
Why Pre-Approval Should Come Before House Hunting
A self-employed borrower should ideally have qualifying income evaluated before seriously shopping for property. A preliminary conversation based only on stated revenue or estimated earnings may not reveal underwriting issues. A more thorough review may include tax returns, ownership documentation, recent financial information, available assets, credit obligations, and the proposed housing payment. Depending on the program and lender, automated underwriting findings may also help evaluate the application. However, a pre-approval is not final loan approval. Property, appraisal, title, insurance, documentation, and other underwriting requirements must still be satisfied. Early preparation helps reduce uncertainty.
Don’t Forget Florida’s Property Expenses
Mortgage affordability is not determined by principal and interest alone. Florida borrowers should also consider homeowners insurance, property taxes, applicable flood insurance, HOA dues, CDD assessments, and mortgage insurance. These expenses can vary considerably between properties. A business owner comparing two homes with similar prices may discover that total monthly housing costs are very different. The objective should be to evaluate a comfortable total payment—not merely the maximum possible purchase price.
What Should Self-Employed Buyers Do First?
Start by understanding how your income will be evaluated. A mortgage professional familiar with self-employed borrowers can review available documentation and help identify possible financing approaches. That may include comparing traditional qualification methods with appropriate alternative-documentation options. The review should also address down payment, closing costs, reserves, credit, and monthly affordability. Business owners often spend years developing a successful company. Applying that same level of preparation to a home purchase is a sensible next step.
Bottom Line
A successful business and a strong mortgage application are not always the same thing. The difference often comes down to how qualifying income is documented and calculated. With mortgage rates elevated and Tampa Bay’s housing market offering different opportunities across neighborhoods, preparation matters. If you’re self-employed and considering purchasing a home in Florida, let’s review your financial picture before you start shopping.
📞 Call or Text Rafi Castro: 813-469-7568 | rafi.mortgage
Mortgage information is educational. Rates are national market averages, not personalized quotes or offers to lend. Program eligibility, qualifying income, loan approval, pricing, and terms depend on applicable guidelines and individual circumstances.
FAQ
Can I qualify for a mortgage if I’m self-employed?
Yes. Self-employed borrowers may qualify for conventional, FHA, VA, USDA, or other programs when they meet applicable eligibility and underwriting requirements.
Do mortgage lenders use gross business revenue?
Generally, traditional mortgage underwriting does not treat gross business revenue as personal qualifying income. Lenders evaluate documented income and applicable adjustments.
Do I need two years of self-employment?
A two-year history is commonly used, but certain programs and circumstances permit exceptions. Requirements vary.
Can depreciation help my mortgage qualification?
Certain depreciation expenses may be considered in cash-flow analysis under applicable guidelines.
Are bank-statement loans available in Florida?
Some lenders offer alternative-documentation mortgage programs for eligible Florida borrowers. Terms, pricing, and qualification requirements vary.
Rafael ‘Rafi’ Castro
Call or text me today . Let’s build a strategy that fits your goals, not just today’s headlines.
Rafael ‘Rafi’ Castro
Mortgage Loan Originator | Marymont Financial Services
NMLS #2380091
Phone: 813.469.7568
Phone: 813.590.0031
Email: rcastro@marymontfs.com
Serving homebuyers throughout Florida