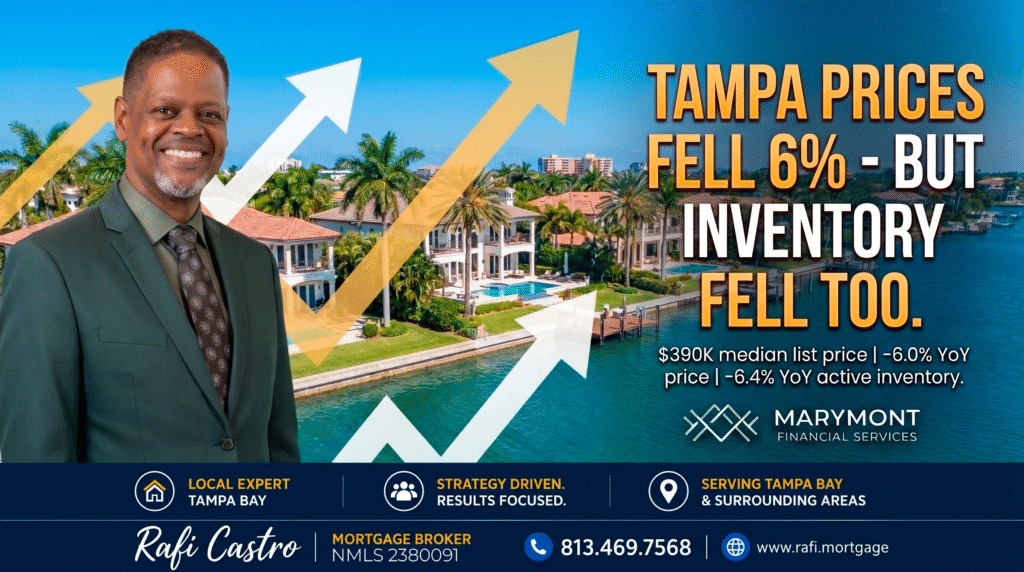
Tampa home asking prices fell 6% in August 2026 while active inventory declined 6.4%. See what the latest Tampa housing and mortgage-rate data means for buyers relocating to Florida.
For context on whether now is a good time to buy, see Redfin’s analysis: Is Now a Good Time to Buy a House?
Moving to Tampa? Home Prices Are Softer – but Buyers Have Fewer Homes to Choose From
Anyone considering a move to Tampa Bay received an interesting set of housing numbers this week. Tampa’s median metro listing price declined to approximately $390,000 in August 2026, down 6% from one year earlier. At first glance, that sounds like an obvious win for buyers. But another number complicates the story. Active listings declined 6.4% year over year to 17,996 properties, even while national inventory increased. So Tampa buyers have softer asking prices – but fewer homes to choose from.
Price Reductions Are Still Common
About 25.5% of Tampa listings received a price reduction in August, compared with roughly one in five listings nationally. That can create negotiating opportunities, but buyers should not assume every seller is desperate. Properties spent a median 74 days on the market, longer than the national median. Longer marketing times can create room to negotiate, particularly on homes that have already experienced price reductions.
Tampa Is a Balanced Market – but Neighborhoods Differ
Separate city-level August data characterized Tampa as a balanced housing market, with a median sold price around $430,000 and homes selling for roughly 98% of asking price on average. Those averages are helpful, but relocation buyers should be careful about applying them to a specific property. Tampa Bay includes dramatically different submarkets. South Tampa, Westchase, Wesley Chapel, Riverview, St. Petersburg, Clearwater, Lakeland and other communities can differ in price, taxes, insurance, CDD fees, HOAs and market competition. The correct analysis starts at the neighborhood – and often the ZIP-code – level.
Mortgage Rates Jumped Above 7% Thursday
Financing also became more challenging this week. Mortgage News Daily reported that its average top-tier 30-year fixed rate reached 7.07% on September 10, up from 6.97% one day earlier and 6.89% Tuesday. Freddie Mac’s weekly survey reported a lower average of 6.76%. Those numbers are not necessarily contradictory. Freddie Mac collects mortgage application data over several days, while Mortgage News Daily’s index responds more immediately to current lender pricing. For a buyer shopping today, daily market changes can matter substantially.
Sources: Freddie Mac, Mortgage News Daily
Why Rates Rose
August’s Producer Price Index showed wholesale prices rising 0.4% during the month and 5.4% year over year. Energy prices also rose sharply during August, helping push the headline inflation number higher. Bond markets reacted negatively. The 10-year Treasury yield climbed toward approximately 4.93% Thursday. Mortgage rates are influenced heavily by the bond market because mortgage-backed securities compete with Treasury securities for investor capital. When Treasury yields rise sharply, mortgage rates generally face upward pressure as well.
Another Inflation Report Comes Next
Markets are watching the next Consumer Price Index release closely. Inflation data can create additional volatility in Treasury yields and mortgage pricing. Rather than trying to predict exactly what one report will do to rates, homebuyers should make sure they are financially prepared for different rate scenarios.
Mortgage Applications Are Slowing – but Purchases Are Holding Up Better
The Mortgage Bankers Association reported that total mortgage applications declined 2.7% for the week ending September 4. Refinance applications fell 6%. Purchase applications, however, declined only 0.2% for the week and remained 4% higher than a year earlier. MBA also reported that adjustable-rate mortgages accounted for 8.5% of applications, suggesting borrowers are increasingly exploring different ways to structure financing as fixed mortgage rates rise.
Relocation Buyers Should Start With the Monthly Payment
People moving to Florida sometimes begin with a purchase-price budget. That can be misleading. Two similarly priced Tampa Bay homes can produce very different monthly payments because of differences in property taxes, homeowners insurance, flood insurance, HOA dues, CDD assessments, mortgage insurance and loan structure. The better approach is to establish a comfortable total housing payment first. Then determine which properties and neighborhoods fit inside it.
Why a $500,000 Home Is Not Always a $500,000 Payment
A buyer may compare two homes with the same purchase price and assume the monthly cost will be similar. In Tampa Bay, that can be a costly assumption. One property may have a CDD, higher insurance exposure or flood insurance requirement while another does not. Property-tax estimates can also change after a sale. Financing should be modeled using the specific property whenever possible, not just a generic price point.
Self-Employed Relocation Buyers Need Additional Planning
Relocation can become more complicated for business owners. A self-employed borrower may need tax returns, K-1s, business returns, business and personal bank statements or other documentation depending on the financing program. Traditional conventional, FHA or VA financing may work for many borrowers. Others may need to evaluate alternative-documentation options such as bank-statement programs. The right strategy depends on the complete financial profile. That analysis should happen before scheduling a weekend full of showings.
What Buyers Should Take From the August Numbers
The August data creates a mixed but potentially useful environment for buyers. Softer asking prices and frequent price reductions can provide leverage on certain properties. At the same time, lower active inventory means buyers cannot assume every neighborhood has abundant choices. The best approach is to identify the specific areas that fit your lifestyle and budget, understand the complete monthly cost, and then evaluate each property based on its own market position.
What Realtors Working With Relocation Buyers Should Consider
For agents helping clients move into Tampa Bay, financing preparation can make the showing process more productive. Before a buyer flies into town, it helps to know the comfortable monthly payment, estimated cash to close, loan-program options and how taxes, insurance, HOA or CDD costs can change affordability. That allows the property search to focus on homes that actually fit the buyer’s financial goals.
Bottom Line
Tampa’s August housing numbers tell a more complicated story than simply saying prices are falling. Asking prices are softer. Price reductions remain common. But inventory is also tighter than a year ago. At the same time, mortgage rates moved above 7% in one major daily index. For people relocating to Tampa Bay, preparation matters. Know the payment. Understand the neighborhood. Review the financing. Then shop for the property.
f you’re considering a move to Florida, send me the area or ZIP code and approximate price range you’re considering. Let’s look at the numbers before the house hunt begins.
📞 Call or Text Rafi Castro: 813-469-7568 | rafi.mortgage
For Florida borrowers. Mortgage rates referenced are national market averages for educational purposes only and are not an offer to lend. Loan approval, rates and terms are subject to qualification, property eligibility, program requirements, underwriting and market conditions.
FAQ
Are Tampa home prices falling in 2026?
Tampa’s median metro listing price was approximately $390,000 in August 2026, about 6% below a year earlier. Conditions vary significantly by neighborhood, property type and price range.
Is Tampa a buyer’s market right now?
The broader city has been characterized as balanced, but Tampa Bay is highly property- and neighborhood-specific. Price reductions are common on some listings, while desirable homes can still move quickly.
Is Tampa housing inventory increasing?
Not in the latest August metro data. Active Tampa listings were approximately 17,996, down 6.4% from a year earlier, even as national active inventory increased.
Why are Freddie Mac and Mortgage News Daily showing different mortgage rates?
The sources use different methodologies and measurement periods. Freddie Mac reports a weekly survey, while Mortgage News Daily follows daily lender pricing more immediately. Both are market averages, not personalized mortgage quotes.
What should someone relocating to Tampa do before house hunting?
Start with a complete financing review and a comfortable total monthly-payment target. Then account for property taxes, homeowners and flood insurance, HOA or CDD costs and the specific neighborhoods being considered.
Can self-employed buyers qualify when relocating to Florida?
Yes. Depending on the borrower, traditional financing may work, while some borrowers may need alternative-documentation programs such as bank-statement financing. Qualification depends on the full financial profile and program requirements.
Rafael ‘Rafi’ Castro
Call or text me today . Let’s build a strategy that fits your goals, not just today’s headlines.
Rafael ‘Rafi’ Castro
Mortgage Loan Originator | Marymont Financial Services
NMLS #2380091
Phone: 813.469.7568
Phone: 813.590.0031
Email: rcastro@marymontfs.com
Serving homebuyers throughout Florida