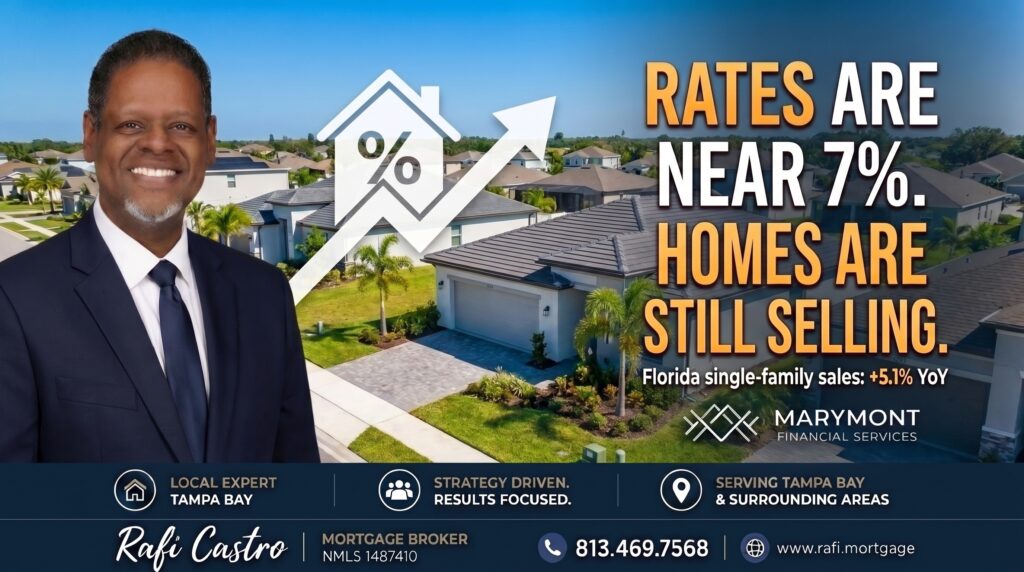
Mortgage rates rose near 7% in early September 2026, yet Florida home sales continue growing. Learn what Tampa Bay homeowners, sellers and buyers should know.
For context on whether now is a good time to buy, see Redfin’s analysis: Is Now a Good Time to Buy a House?
Rates Are Near 7%—So Why Are Florida Homes Still Selling?
Mortgage rates started September moving in the wrong direction for homebuyers. Freddie Mac reported on September 3 that the average 30-year fixed mortgage rate increased to 6.71%, while more immediate daily mortgage-rate tracking was in the upper-6% range. Those numbers create real affordability challenges. Yet Florida buyers continue purchasing homes.
Sources: Freddie Mac
Florida Sales Have Increased for 11 Consecutive Months
Florida Realtors reported that July represented the 11th consecutive month in which closed sales increased year over year for both major residential property categories. Single-family closed sales increased 5.1% from July 2025, while condo and townhouse sales increased 11%. New pending single-family sales also increased 2.4%. The statewide median sale price for an existing single-family home was $425,000, up 3.7% year over year.
Buyers Are Moving Without Waiting for Perfect Rates
That may be one of the most important housing trends of the summer. Buyers did not suddenly receive dramatically lower mortgage rates. Instead, some reached a point where they could no longer—or no longer wanted to—put life decisions on hold. Families grow, jobs change, people relocate, couples marry, owners downsize and renters decide they are ready to purchase. Those life events continue regardless of financial-market conditions.
Tampa Bay Buyers Remain Selective
The Tampa metro market presents its own dynamics. Recent July data showed roughly 18,292 active listings, a median listing price around $397,000 and homes spending approximately 72 days on the market. That means today’s Tampa Bay buyer generally has more time to evaluate a property than buyers had during the pandemic-era frenzy. Sellers need to understand that shift.
The Total Monthly Housing Cost Matters
Today’s buyers are especially sensitive to the complete monthly housing expense. That includes principal and interest, property taxes, homeowners insurance, flood insurance where applicable, HOA or CDD costs, mortgage insurance when required, and expected repairs and maintenance. As borrowing costs rise, each of those expenses becomes more important.
Pricing Correctly Matters Again
A seller may still be able to sell successfully in today’s market, but the strategy is different. Starting substantially above market value and waiting for buyers to negotiate down can backfire. Buyers have alternatives. When a property accumulates significant market time, buyers may begin assuming the seller is unrealistic or that something is wrong with the home. Accurate pricing from the beginning can help avoid that problem.
Seller Concessions Can Be a Financing Tool
Price reductions are not the only tool sellers have. Suppose a seller has room to negotiate $10,000. Reducing the purchase price is one possibility. Another may be using some of that negotiating room as an allowable seller contribution toward eligible buyer closing costs, prepaid expenses or a mortgage rate buydown. Depending on the loan and borrower, reducing the buyer’s upfront cash or mortgage rate could create a greater immediate benefit than an equivalent purchase-price reduction. The correct answer depends on the transaction.
Why Realtors and Lenders Should Run the Numbers Together
This is why the Realtor and mortgage professional should evaluate the numbers before the offer structure is finalized. A price reduction, seller credit and rate buydown can produce very different results in monthly payment and cash to close. When those scenarios are compared early, the buyer and agent can negotiate based on the buyer’s actual goals rather than assumptions.
Mortgage Rates and the 10-Year Treasury
Mortgage rates moved higher early this week as bond yields climbed. The 10-year Treasury yield moved into the upper-4% range. Mortgage rates are influenced heavily by the bond market and do not move directly with the Federal Reserve’s overnight policy rate. Mortgage-backed securities compete with Treasury securities for investors, so mortgage rates often move in the same general direction as Treasury yields. Inflation expectations, government borrowing, economic growth, energy prices and geopolitical developments can all influence those yields.
The Next Economic Reports Matter
The mortgage market now turns toward additional employment and inflation data. These reports can quickly change investor expectations and move both Treasury yields and mortgage pricing. A weaker-than-expected economic report can sometimes help bonds and mortgage rates, while stronger data or renewed inflation concerns can have the opposite effect. That uncertainty is another reason buyers should avoid trying to perfectly predict the market.
Buyers Are Still Applying
Recent Mortgage Bankers Association data showed total mortgage applications increasing modestly, with purchase applications also moving higher for the week. The numbers are not evidence of a booming market. They are evidence that buyers remain engaged even when affordability is challenging.
What Tampa Bay Sellers Should Take Away
Today’s market is not 2021, but it is not frozen either. For homeowners considering a sale, the better questions are: How does my home compare with competing properties? What objections will buyers have? How much does insurance affect affordability? Is the home priced correctly? Could financing incentives make the property more attractive? Those questions matter much more than simply asking whether mortgage rates are high or low.
Buyers Can Use the Same Logic in Reverse
Higher rates are not good news for buyers, but fewer aggressive buyers can create leverage. A seller willing to contribute toward closing costs or financing may create an opportunity that did not exist when buyers were competing with numerous offers. Instead of asking whether the entire market is a buyer’s market, ask what leverage exists on the specific property.
Bottom Line
Mortgage rates are again in the upper-6% range, but Florida housing activity continues. That combination tells us today’s market is being driven by more than rates alone. Buyers are selective. Sellers need better strategy. And financing can become part of the negotiation.
If you’re selling a home in Florida—or you’re a Realtor working with a seller—I’d be happy to help evaluate how different financing structures could affect potential buyers. Let’s run the numbers before the next price reduction.
📞 Call or Text Rafi Castro: 813-469-7568 | rafi.mortgage
For Florida borrowers. Mortgage rates referenced are national market averages for educational purposes only and are not an offer to lend. Loan approval, rates and terms are subject to qualification, property eligibility, program requirements, underwriting and market conditions.
FAQ
Are Florida homes still selling despite higher mortgage rates?
Yes. Florida’s July 2026 data showed year-over-year increases in closed sales for both single-family homes and condos/townhouses, even with mortgage rates remaining elevated.
What was Florida’s median single-family home price in July 2026?
The statewide median sale price for an existing single-family home was approximately $425,000, up 3.7% year over year.
Should a Tampa Bay seller automatically reduce the price if a home is sitting?
Not necessarily. Pricing should be evaluated against current comparable sales and competition. Depending on the transaction, an allowable seller contribution toward closing costs or a rate buydown may also be worth comparing with a price reduction.
How can a seller credit help a buyer?
Subject to loan-program limits and underwriting rules, seller contributions may help pay eligible closing costs, prepaid expenses or certain financing costs. The impact should be calculated for the specific borrower and loan.
Do mortgage rates move directly with the Federal Reserve?
No. Mortgage rates are strongly influenced by the bond market, including mortgage-backed securities and Treasury yields. Fed policy and expectations matter, but mortgage rates can move before or independently of a Fed rate decision
Rafael ‘Rafi’ Castro
Call or text me today . Let’s build a strategy that fits your goals, not just today’s headlines.
Rafael ‘Rafi’ Castro
Mortgage Loan Originator | Marymont Financial Services
NMLS #2380091
Phone: 813.469.7568
Phone: 813.590.0031
Email: rcastro@marymontfs.com
Serving homebuyers throughout Florida